Dollar-cost averaging — How market volatility can work to your advantage
When markets fall, your immediate thought might be to sell. What you don’t realize is that if you try to time the market, it could cost you more to leave than to stay invested.
If you try to predict the market, you might miss out on the best days.
Often, when markets recover, it happens suddenly and leaves little time for investors to react.
In this example, you can see that if John tried to time the market and missed out on the 10 best days in the process, he could have potentially missed out on half of the returns he could have earned if he had stayed invested the whole time. His actions potentially cost him over $20,000 in returns!
Growth of $10,000 in S&P/TSX Composite Total Return Index*
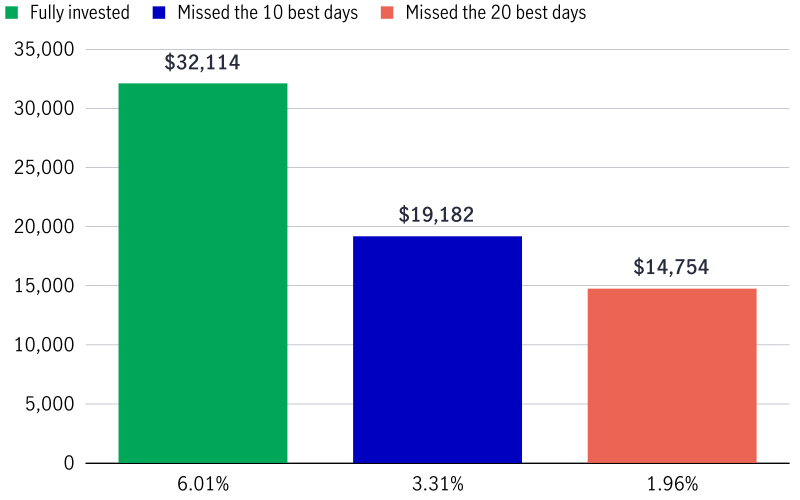
Hypothetical example of illustrative purposes only. *
Important disclosure
Important disclosure
*Source: Bloomberg, Manulife Investment Management, as of September 30, 2026. For illustration purposes only. Average 1yr return calculated by annualizing the average daily return assuming 280 trading days in a year. May not exactly match actual annualized returns due to calculation methodology. Past performance is not indicative of future performance. Index: S&P/TSX Composite Total Return Index. The index is unmanaged and cannot be purchased directly by investors. The rate of return shown is used only to illustrate the effects of the compound growth rate and is not intended to reflect future values of the investment fund or returns on investment in the investment fund.
There’s another way to deal with market fluctuations, and that’s with dollar-cost averaging (DCA).
Dollar-cost averaging doesn’t tell you what investment to buy (that’s between you and your advisor), but it does away with the problem of trying to figure out when to buy. With dollar-cost averaging, you spread out your purchase in equal installments over a pre-determined period of time.
So, let’s say you purchase $100 worth of units of the same investment every week. With fluctuations in the marketplace, sometimes the cost per unit will be higher, sometimes it will be lower. When the price is lower, you end up buying more units than when the price is higher.
Over time, it works out that you buy more units when the price is low and you may end up with more units in total than you would if you tried to figure out when the market was going to provide you with the best outcome.
Dollar-Cost Averaging at work

For illustration purposes only.

How can DCA help you?
Provide a disciplined approach — DCA helps make sure that you don’t try to “time” the market and that you continue to invest even when markets are down (with opportunities to invest at lower prices).
Give you peace of mind — Regular contributions means not having to worry about investing at a “high” point in the market or missing an opportunity to invest at low prices. As a result, you may receive, over time, a more average investment price.

Is DCA right for you?
- If you’re looking for an investment strategy that may help manage the impact of market volatility over time
- If you want to make regular contributions instead of lump sum payments
By staying invested, you won’t miss out on the best days that make up some of the market growth. Strong performance occurs on a handful of single days over a longer period. There’s no way to predict these strong days. Also, by using the dollar-cost averaging approach, it may help smooth out market fluctuations, and over time, it can help lower the average price per unit purchased and provide the potential for higher capital appreciation.

How does DCA work?
For more information on Manulife’s dollar-cost averaging products, click here.
Important disclosure
Important disclosure
This document is provided as a general source of information and should not be considered personal, legal, accounting, tax or investment advice, or construed as an endorsement or recommendation of any entity or security discussed. Every effort has been made to ensure that the material contained in this document is accurate at the time of publication. Market conditions may change which may impact the information contained in this document. All charts and illustrations in this document are for illustrative purposes only. They are not intended to predict or project investment results. Individuals should seek the advice of professionals, as appropriate, regarding any particular investment. Investors should consult their professional advisors prior to implementing any changes to their investment strategies.
Manulife Funds are managed by Manulife Investment Management Limited. Manulife Investments is a trade name of Manulife Investment Management Limited. Manulife, Manulife & Design, Stylized M Design, and Manulife Investments are trademarks of The Manufacturers Life Insurance Company and are used by it and by its affiliates under license.
RO 6053639